Insights from 2023 Cyber Claims Study Webinar

by Michael Bruemmer 4 min read February 12, 2024

Review of Findings & Front-line Insights

Panel Participants:

  • Richard Goldberg (Moderator) – Constangy, Brooks, Smith & Prophete, LLP
  • Michael Bruemmer – Experian
  • Sean Renshw – RSM US, LLP
  • Mark Greisiger – NetDiligence

About NetDiligence Cyber Claims Study

It is NetDiligence’s 13th year of doing this Cyber Claims Study. A total of 9,028 claims were analyzed during the past five years 2018-2022.
An observation from the over 9,000 Cyber Claims (5000 of which are brand new claims this past year in 2023) analyzed is while many of the categories over the last five years have remained the same, the data has changed, sometimes dramatically.

About Experian

We provide call center coverage, notification coverage, as well as, identity theft protection, and all the consumer resolutions that go along with it for about 5000 data breaches every year, and I was delighted to be on the panel.

Key Insights

Experian has proudly sponsored the annual NetDiligence Cyber Claims Study for three years. During this time, I’ve witnessed companies adapt and transform their operations to confront the growing tide of cyber threats. The evolution of their infrastructure to anticipate and respond to these challenges has been remarkable and necessary. However, despite my front-row seat in this fast-changing landscape, the results of each study never fail to surprise and intrigue me.

The insights from the latest study, conducted in 2023, continue to shape our understanding of the evolving cyber landscape.

Ransomware’s Dominance

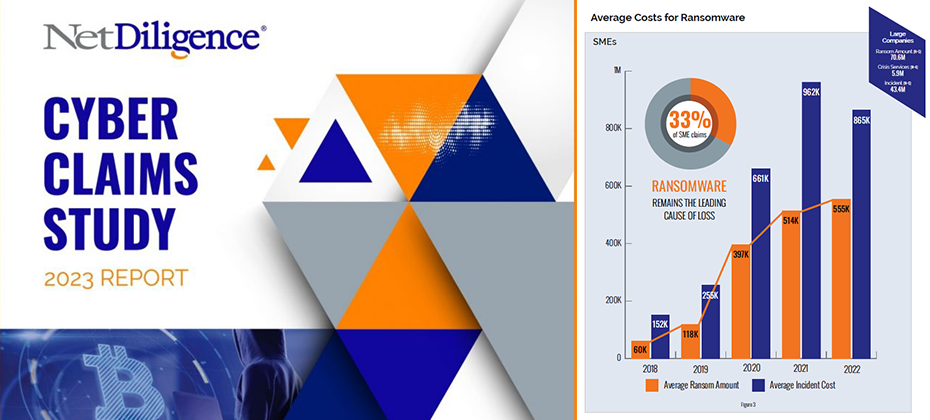
Mark kicked off the discussion by shedding light on the escalating costs associated with cyber incidents. In 2022, the average incident cost for SME organizations remained stable at $169,000 (similar to the combined five-year window from 2018 to 2022 at about 175,000). However, there was a substantial increase for large companies, reaching $20.3 million in 2022 (and if you look at the five-year average, it was about 13 million). This surge raised eyebrows and set the stage for a deep dive into ransomware, a leading cause of concern.

Examining Ransomware Trends

The conversation swiftly shifted to ransomware, a pervasive threat in the cyber insurance landscape. As I stated, at Experian we see a correlation between the rise in ransomware and third-party breaches. Most of the industry experts on the panel participate in a Ransomware Advisory Group together. Mark brought up a good insight from our advisory group on the brazen tactics employed by threat actors lately, showcasing their intimate knowledge of the cyber insurance world.

Business Sectors Under Siege

Richard and Sean added to the discussion the top ten business sectors affected by ransomware, with professional services leading the pack. The impact on technology, with a payout of $830,000, stood out as well.

Beyond Ransomware

The conversation broadened to encompass other types of losses, such as social engineering and business email compromise. The focus on business interruption emerged as a key concern for cyber insurance claims, with the industry grappling with criminal acts versus non-criminal acts.

Looking Ahead

As the discussion unfolded, industry experts, including myself, expressed eagerness to anticipate the future cyber landscape. Predictions range from the industry mutating to the emergence of new players in the nation-state game. The role of artificial intelligence and innovative solutions from new vendors becomes a focal point of interest.

In conclusion, the NetDiligence Cyber Claims Study 2023 Report paints a vivid picture of the challenges and transformations within the cyber insurance domain. The increasing sophistication of threat actors, coupled with evolving business strategies, sets the stage for continuous adaptation and innovation in the fight against cyber threats. As we look ahead, the resilience of businesses and the collaboration between industry stakeholders will play a pivotal role in shaping the cybersecurity landscape. I invite you to access the report and view the discussion replay for a deeper understanding of the challenges and transformations within the cyber insurance claims domain.

Get NetDiligece Cyber Claims Study resources on-demand now!

NetDiligence’s latest Cyber Claims Study and Webinar, sponsored by Experian Data Breach, is available on-demand. This report serves as a resounding call to action, prompting businesses to ready themselves against cyber threats. Dive in to get insights and stay one step ahead of cyber adversaries.


Related Posts

Cash Flow Insights: Powering the Next Evolution in Lending

For decades, credit data has given lenders a trusted foundation for assessing risk. Now, consumer-permissioned cash flow data is adding another layer of insight into consumers’ financial lives, including income, spending, liquidity and changing financial obligations. The opportunity is significant. Nearly one in five consumers lacks access to or has damaged credit. New Experian research also shows that 60% of consumers who have previously been denied credit or received less favorable terms than expected believe the outcome would have been different if lenders had considered their recent income and banking activity alongside their credit history. 1,2 For lenders, cash flow insights can provide additional context about a consumer’s financial capacity and support more informed underwriting decisions. The next challenge is making those insights easier to use consistently and responsibly at scale. What are cash flow insights? Cash flow insights are derived from consumer-permissioned banking data and provide visibility into how money moves into and out of a consumer’s accounts. Depending on the information available, cash flow data can provide insight into financial behaviors such as: Income and income stability: Regular and irregular income streams and changes over time Spending and recurring expenses: Everyday spending patterns and ongoing financial obligations Account balances and liquidity: Available funds and changes in account balances Debt obligations: Loan payments and other recurring debt commitments Cash flow patterns: How money moves into and out of accounts over time Traditional credit information provides a rich history of how consumers have managed credit. Cash flow insights add context about their current financial activity and capacity, providing lenders with a more complete view of financial health. Cash flow insights can also add predictive value to risk assessment. Experian analysis shows Cashflow Score can deliver up to a 25% lift in predictive performance over conventional credit scores when tailored to targeted risk tiers.3 How lenders can put cash flow insights to work at scale As interest in cash flow insights grows, the conversation is moving beyond what the data can reveal to how financial institutions can use it consistently and responsibly. That requires standardized consumer reporting, clear governance and decision-ready insights that can work within established lending processes. The launch of Experian Cashflow Data Bureau at Vision 2026 reflects this shift from access to adoption. The new consumer reporting agency operates under the Fair Credit Reporting Act (FCRA) and is designed to help financial institutions adopt consumer-permissioned cash flow insights at scale. A key part of that foundation is the cash flow consumer report, which organizes consumer-permissioned banking information into a standardized consumer report regulated under the FCRA. This gives lenders a consistent foundation for incorporating cash flow information into lending decisions while providing consumers with access to the information in their report. Turning greater visibility into better decisions The next evolution in credit isn’t about choosing between traditional credit and cash flow data. Each provides a different perspective. Traditional credit information offers deep insight into how consumers have managed credit over time. Cash flow insights can add context about financial activity and capacity. Bringing those perspectives together can give lenders greater visibility into consumers’ financial health and help them better distinguish between risk and resilience, support more informed decisions and identify opportunities to responsibly expand access to credit. As cash flow adoption continues to grow, its value will come from how effectively it complements the information lenders already use. The opportunity isn't simply to see more data. It's to turn that additional visibility into smarter, more informed decisions. Explore how Experian Cashflow Data Bureau is helping financial institutions put consumer-permissioned cash flow insights into practice at scale. Learn more [1] Federal Reserve Bank of New York, The Market for Credit Building: Demand, Product Characteristics and Consumer Uses, 2026. [2] Experian commissioned Atomik Research to conduct an online survey of 2,000 U.S. adults age 18+. Fieldwork took place July 16–21, 2026. Margin of error: +/- 2.2 percentage points at a 95% confidence level. [3] Based on Experian analysis when Cashflow Score is compared with conventional credit scores, tailored to targeted risk tiers. Predictability based on KS.

October 14, 2026 by Julie Lee
The Three Onboarding Fraud Pain Points That Slow Growth (And How to Solve Them) 

Effective fraud prevention is critical to balancing security and customer experience during onboarding. Learn more!

October 12, 2026 by Charles Hunter
How Rental Data Is Expanding Financial Opportunity for Millions of Renters 

Discover how rental payment reporting can expand credit access, strengthen credit profiles and improve risk assessment for renters and housing providers.

October 8, 2026 by Manjit Sohal

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe
