Industries
Millions of consumers lack credit history and/or have difficulty obtaining credit from mainstream financial institutions. To ease access to credit for “invisible” and below prime consumers, financial institutions have sought ways to both extend and improve the methods by which they evaluate borrowers’ risk. This initiative to effectively score more consumers has involved the use of alternative credit data.1 Alternative credit data is FCRA-compliant data that is typically not included in a traditional credit report and is used to deliver a more complete view into a consumer’s creditworthiness. “Alternative credit data helps us paint a fuller picture of a consumer so they can get better access to the financial services they need and deserve,” said Alpa Lally, Vice President of Data Business at Experian. Experian recently sponsored the FinovateSpring conference in San Francisco, where Alpa had a chance to sit down with Jacob Gaffney, Editor-in-Chief of the HousingWire News Podcast, to discuss ways consumers can improve their credit scores. As an immigrant, Alpa spoke personally about the impact of having a limited credit history and how alternative credit data can help drive greater access to credit for consumers and profitable growth for lenders through more informed lending decisions. Highlights include: How alternative and traditional credit data differ Types of alternative credit data being used by lenders How “credit-invisibles” can best leverage alternative credit data Alternative credit data product solutions, including Experian BoostTM Listen now 1When we refer to “Alternative Credit Data,” this refers to the use of alternative data and its appropriate use in consumer credit lending decisions, as regulated by the Fair Credit Reporting Act. Hence, the term “Expanded FCRA Data” may also apply in this instance and both can be used interchangeably.
To create a socially credible environment, China has developed a mobile app to alerts users when they are within a 500-meter radius of someone in debt.
The shift from banking to digital is apparent. Here are a few ways that financial services can adjust to changing consumer behavior. Read more!
First-party fraud involves making financial commitments or using their own identity, a manipulated version of their own identity or a synthetic identity.
Even with the Fed’s gradual 2018 rate hikes, consumers are shopping. Usage of credit cards is on the rise in 2018 and only expected to grow.
Experian recently interviewed Philip Bohi, Vice President for Compliance Education of AFSA, to learn more about his perspective on alternative data.
Rather than reinventing the wheel, companies can leverage existing services to build more complex solutions and launch faster with APIs.
Financial services lenders and businesses are increasingly seeking to leverage enhanced digital marketing channels, but how does regulatory play into the mix?
Market trends and insight from Q1 2018. The economy remains steady as we transition from 2017. Keep an eye on inflation and interest rates.
CFSI’s Thea Garon talks about a free, open-source tool from the organization to help financial institutions drive consumer financial health.
The second full day of Experian Vision 2018 featured Capt. Mark Kelly and former congresswomen Gabby Giffords, a series of diverse breakout sessions and concluded with Super Bowl-winning quarterback Aaron Rodgers.
The first full day of Vision 2018 featured in-depth talks on alternative credit data, enhanced credit marketing, faster decisioning, fraud and identity protections and the latest in tech innovation.
In an all-new report, Experian dives into “The State of Alternative Credit Data,” providing in-depth coverage on how alternative credit data is defined, consumer personas, and how this data complements traditional credit data files.
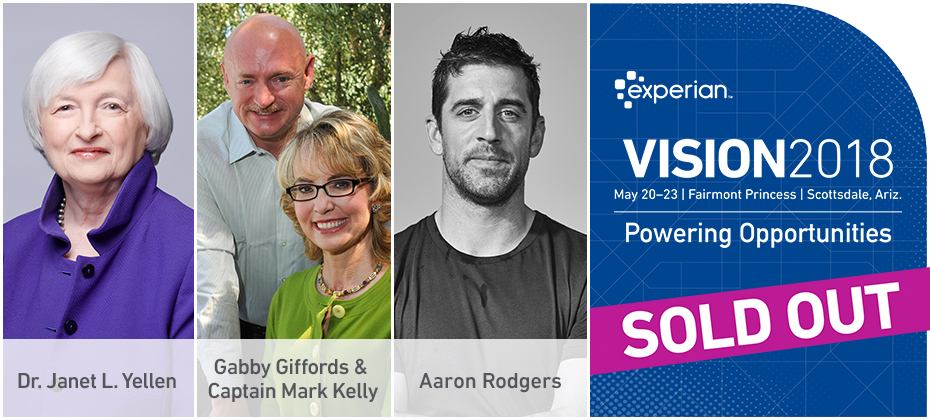
Experian’s annual Vision Conference kicks off to a sold-out crowd in Scottsdale, Ariz., bringing together some of the industry’s top thought leaders in financial services, tech, data science and information security.
There is a delicate balance in delivering a digital experience that instills confidence while providing easy and convenient account access. When it comes to a frictionless, secure customer experience, consider these findings