The Ultimate Guide to Credit Card Fraud Detection

by Julie Lee 5 min read July 23, 2024

With debit and credit card transactions becoming more prevalent than cash payments in today’s digital-first world, card fraud has become a significant concern for organizations. Widespread usage has created ample opportunities for cybercriminals to engage in credit card fraud. As a result, millions of Americans fall victim to credit card fraud annually, with 52 million cases reported last year alone.1

Preventing and detecting credit card fraud can save organizations from costly losses and protect their customers and reputations. This article provides an overview of credit card fraud detection, focusing on the current trends, types of fraud, and detection and prevention solutions.

What is credit card fraud?

Credit card fraud involves the unauthorized use of a credit card to obtain goods, services or funds. It’s a crime that affects individuals and businesses alike, leading to financial losses and compromised personal information. Understanding the various forms of credit card fraud is essential for developing effective prevention strategies.

Types of credit card fraud

Understanding the different types of credit card fraud can help in developing targeted prevention strategies. Common types of credit card fraud include:

  • Card not present fraud occurs when the physical card is not present during the transaction, commonly seen in online or over-the-phone purchases. In 2023, card not present fraud was estimated to account for $9.49 billion in losses.2
  • Account takeover fraud involves fraudsters gaining access to a victim’s account to make unauthorized transactions. In 2023, account takeover attacks increased 354% year-over-year, resulting in almost $13 billion in losses.3,4
  • Card skimming, which is estimated to cost consumers and financial institutions over $1 billion per year, occurs when fraudsters use devices to capture card information from ATMs or point-of-sale terminals.5
  • Phishing scams trick victims into providing their card information through fake emails, texts or websites.

What is credit card fraud prevention and detection?

To combat the rise in credit card fraud effectively, organizations must implement credit card fraud prevention strategies that involve a combination of solutions and technologies designed to identify and stop fraudulent activities. Effective fraud prevention solutions can help businesses minimize losses and protect their customers’ information. Common credit card fraud prevention and detection methods include:

  • Fraud monitoring systems: Banks and financial institutions employ sophisticated algorithms and artificial intelligence to monitor transactions in real time. These systems analyze spending patterns, locations, transaction amounts, and other variables to detect suspicious activity.
  • EMV chip technology: EMV (Europay, Mastercard, and Visa) chip cards contain embedded microchips that generate unique transaction codes for each purchase. This makes it more difficult for fraudsters to create counterfeit cards.
  • Tokenization: Tokenization replaces sensitive card information with a unique identifier or token. This token can be used for transactions without exposing actual card details, reducing the risk of fraud if data is intercepted.
  • Multifactor authentication (MFA): Adding an extra layer of security beyond the card number and PIN, MFA requires additional verification such as a one-time code sent to a mobile device, knowledge-based authentication or biometric/document confirmation.
  • Transaction alerts: Many banks offer alerts via SMS or email for every credit card transaction. This allows cardholders to spot unauthorized transactions quickly and report them to their bank.
  • Card verification value (CVV): CVV codes, typically three-digit numbers printed on the back of cards (four digits for American Express), are used to verify that the person making an online or telephone purchase physically possesses the card.
  • Machine learning and AI: Advanced algorithms can analyze large datasets to detect unusual patterns that may indicate fraud, such as sudden large transactions or purchases made in different geographic locations within a short time frame. Advanced algorithms can analyze large datasets to detect unusual patterns that may indicate fraud, such as sudden large transactions or purchases made in different geographic locations within a short time frame.
  • Behavioral analytics: Monitoring user behavior to detect anomalies that may indicate fraud.
  • Education and awareness: Educating consumers about phishing scams, identity theft, and safe online shopping practices can help reduce the likelihood of falling victim to credit card fraud.
  • Fraud investigation units: Financial institutions have teams dedicated to investigating suspicious transactions reported by customers. These units work to confirm fraud, mitigate losses, and prevent future incidents.

How Experian® can help with card fraud prevention and detection

Credit card fraud detection is essential for protecting businesses and customers. By implementing advanced detection technologies, businesses can create a robust defense against fraudsters. Experian® offers advanced fraud management solutions that leverage identity protection, machine learning, and advanced analytics. Partnering with Experian can provide your business with:

  • Comprehensive fraud management solutions: Experian’s fraud management solutions provide a robust suite of tools to prevent, detect and manage fraud risk and identity verification effectively.
  • Account takeover prevention: Experian uses sophisticated analytics and enhanced decision-making capabilities to help businesses drive successful transactions by monitoring identity and flagging unusual activities.
  • Identifying card not present fraud: Experian offers tools specifically designed to detect and prevent card not present fraud, ensuring secure online transactions.

Take your fraud prevention strategies to the next level with Experian’s comprehensive solutions. Explore more about how Experian can help.

Sources

1 https://www.security.org/digital-safety/credit-card-fraud-report/

2 https://www.emarketer.com/chart/258923/us-total-card-not-present-cnp-fraud-loss-2019-2024-billions-change-of-total-card-payment-fraud-loss

3 https://pages.sift.com/rs/526-PCC-974/images/Sift-2023-Q3-Index-Report_ATO.pdf

4 https://www.aarp.org/money/scams-fraud/info-2024/identity-fraud-report.html

5 https://www.fbi.gov/how-we-can-help-you/scams-and-safety/common-scams-and-crimes/skimming

This article includes content created by an AI language model and is intended to provide general information.


Related Posts

2026 Fintech Identity and Fraud Report

Explore the Fintech Identity and Fraud Report for insights on AI-driven fraud threats, identity protection and the evolving fraud landscape.

September 28, 2026 by Laura Davis
Who’s Driving What? How Fuel Loyalty and Generational Preferences are Shaping the Vehicle Market

Take a look around at any road, parking lot, or highway, and you’ll see just how diverse today’s vehicle landscape has become. Within that evolving mix, electric vehicles (EVs) have seen years of rapid growth, and while the market is seemingly entering a new phase, interest remains. So, with several vehicles and fuel types to choose from, what keeps drivers coming back to electrified vehicles? Experian Automotive’s Automotive Market Trends Report: Q2 2026 found that among EV owners who returned to the market in the last 12 months, majority (72.2%) replaced their EV with another EV, while 18.5% switched to a gasoline vehicle. Hybrid buyers also showed considerable loyalty to electrification, with 55.7% of gas-hybrid owners staying with the same fuel type when replacing their vehicle, and 32.7% swapping for a gasoline vehicle. Consumers are seemingly remaining loyal to EVs and hybrids because they are attracted to the benefits that fit their everyday lifestyle, such as lower fuel or charging costs amid the elevated gas prices. For some, it could also be tied to convenience, as drivers who have found a reliable charging routine or appreciate the efficiency of a hybrid may have little reason to switch back to a traditional gasoline vehicle. Generations are taking different paths to electrification Generational differences also influence hybrid and EV loyalty, with younger consumers generally showing greater openness to alternative fuel types. While older generations tend to have greater familiarity with traditional gasoline vehicles, hybrid and EV adoption is increasing across all age groups as these options become more accessible and mainstream. Millennials, in particular, showed the strongest inclination toward electrified vehicles. Through Q2 2026, they accounted for the highest EV share at 8.2%, compared with Gen X at 5.5%, Gen Z (4.7%), and Baby Boomers (4.7%). The difference becomes even more pronounced when hybrids are in the mix, as 23.1% of Millennial registrations were gas-electric hybrids or plug-in hybrids, versus 16.7% for Gen X, 16.8% for Gen Z, and 18.0% for Baby Boomers. For automotive professionals, these differences make understanding who is driving what, and what they may choose next, increasingly important. The future of the automotive market may be less about consumers choosing one vehicle type over the other and more about understanding the distinct patterns and preferences of each generation. As the market continues to evolve, those insights can help automotive professionals better meet consumers where they are. To learn more about vehicle market trends, view the full Automotive Market Trends Report: Q2 2026 presentation on demand.

September 24, 2026 by John Howard
New Data Available for MBS Investors: Current Credit Score 

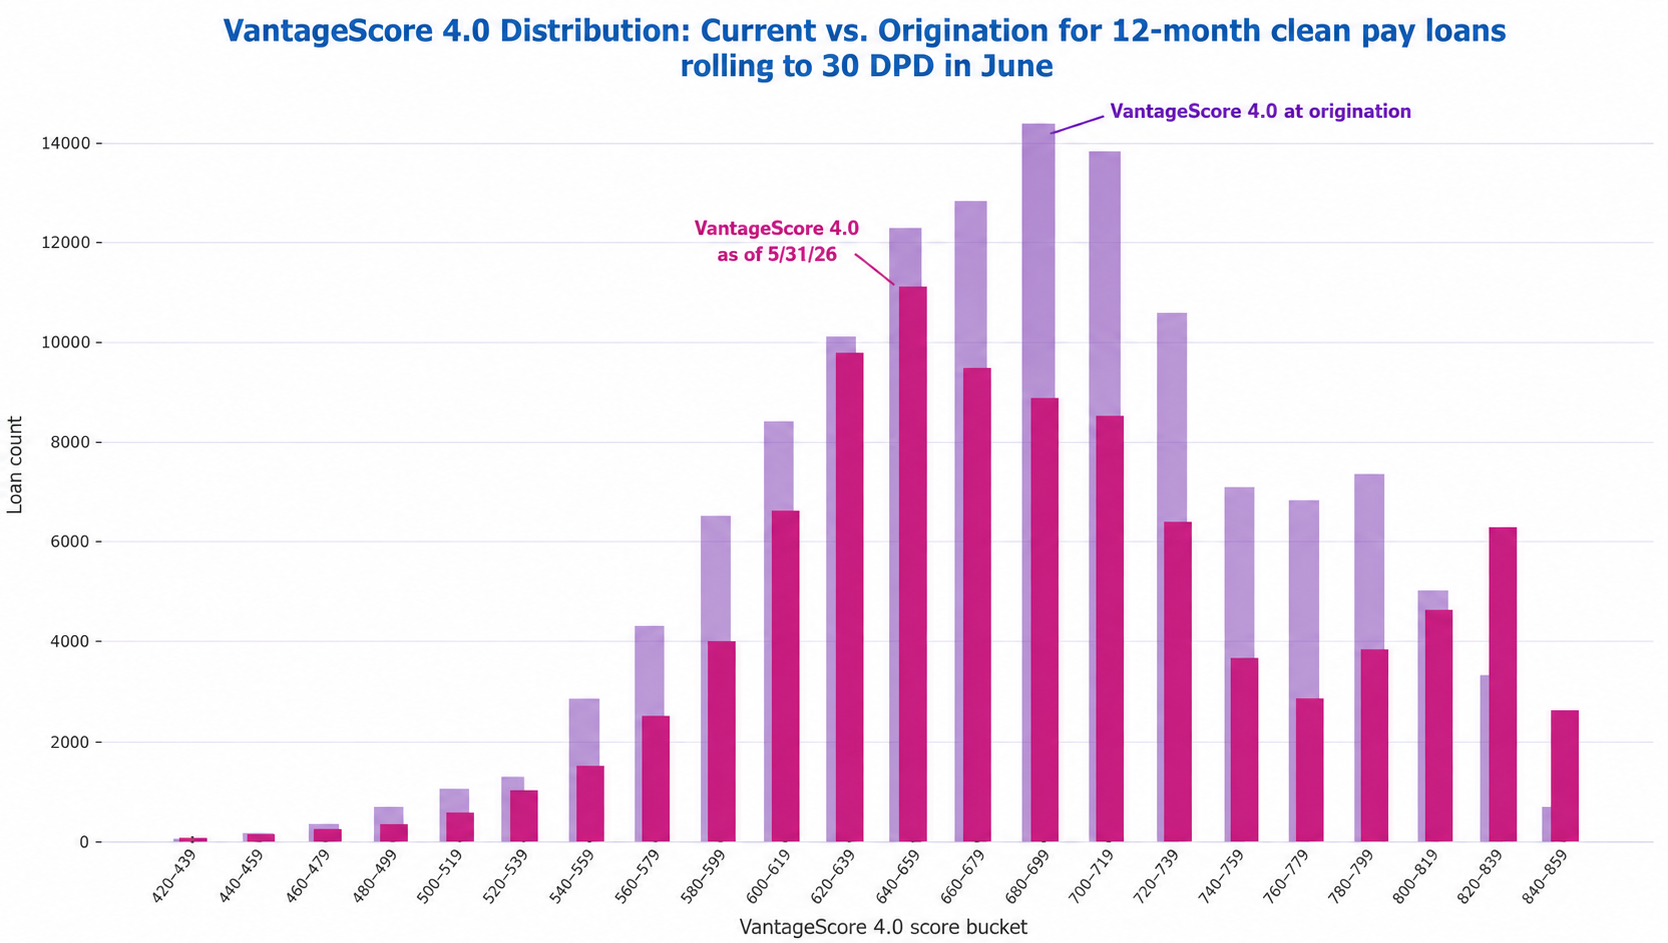
In a previous post, we described how every mortgage borrower’s financial situation and credit profile evolve over time.  After a borrower opens a loan, their financial status evolves—jobs are gained and lost; incomes can rise or fall, and financially stressful situations or windfalls can occur. These effects are often reflected in the consumer’s evolving credit score, which changes with the consumer’s payment behavior on open loans, credit inquiry activity, credit card utilization, and other revolving lines, among other things.    Even though MBS, whole loan, and MSR investors ultimately bear borrower credit risk, they may have access to less current borrower credit information than other participants in the mortgage ecosystem.   In securitized markets (both agency MBS and private-label MBS), updated scores are not provided in disclosure to bondholders, even as loans age year over year.  In whole loan and MSR markets, a single origination credit score is often provided at the time of bid, and after a successful bid, the investor may have a permissible purpose to pull individual scores on an owned portfolio. But until recently, there was no single loan-level dataset that included continuously refreshed credit scores across the U.S. mortgage market—the type of foundational dataset needed to build and tune credit and prepayment models.  A monthly-refreshed Current Credit Score field meets our three-pronged materiality standard for new data delivery to MBS markets:  New: Provides information not available in existing datasets (i.e., orthogonal to currently available data). Neither private-label MBS nor agency MBS standard market data includes a monthly-refreshed borrower credit score.  Material: Impacts a sizeable portion of the MBS universe. For the vast majority of loans in MBS, borrowers credit scores are available.  Significant: Differentiates collateral performance by a large enough margin to influence trading and risk management decisions.  A current credit score wraps all of a borrower’s credit-related behaviors into a single numerical value and has historically been associated with a borrower’s likelihood of becoming 60+ days past due on any obligation within the subsequent 24 months.    In fact, a current credit score is among the most informative indicators of near-term mortgage default risk, as shown in the image below, which depicts 30+ DPD rates by current credit score bands for the entire U.S. mortgage market, controlling for origination score <=650.    Without access to current credit scores, investors are limited to the score at origination—causing the four distinct performance trends shown here to appear as a single averaged line. In reality, score migration since origination reveals significant divergence in credit risk, with the lowest current-score bucket exhibiting a nearly 10 times higher 30+ DPD rate than the highest-score bucket in the latest period shown.  Source:  Experian Mortgage Loan Performance (MLP) dataset hosted on IVolatility DataDriven Platform  In this article, we’ll take a quick look at how score migration acts as an early predictor of a performing loan’s first roll into 30-day delinquent status.    MBS Investors’ Current Credit Score Blindspot: Solved   An MBS investor relying on standard market data and securitization remittance reports sees no sign of borrower stress until the subject mortgage loan in the securitization misses a payment and is reported at 30 days delinquent. Of course, in the vast majority of cases, a borrower begins struggling financially well before missing a mortgage payment:  The borrower may miss payments on other types of loans (credit card, auto loan, personal unsecured, or payday loans) as they prioritize their home and mortgage.  Outstanding balances on credit cards may grow as the borrower begins to make only minimum payments on revolvers.  The borrower may apply for additional credit cards, personal or payday loans   The borrower may apply to increase limits on existing credit cards as outstanding balance nears spending limit  All these stress-indicative behaviors result in a decreasing credit score, many months before the borrower misses their first mortgage payment. An MBS investor with access to each borrower’s current credit score, refreshed each month, can predict increased likelihood of default many months before the first missed mortgage payment—and is therefore at a major information advantage relative to the market generally.  Experian’s Mortgage Loan Performance (MLP) dataset contains thousands of fields describing mortgage performance from each borrower, loan, and property perspective, all refreshed monthly (including, amongst other things, new credit scores and refinance inquiry activity, loan performance on all types of debt, filed junior liens, and AVM values).   MLP is much more comprehensive than loan-level data provided by Freddie Mac, Fannie Mae, Ginnie Mae, and PLS data vendors in several ways:   Standard market datasets may not contain certain data elements that some market participants consider useful when evaluating mortgage prepayment or credit performance. Basic, critical fields such as the borrower’s current credit score and the current junior lien balance on the property are missing.    MLP contains borrower, loan, and property data fields spanning a broad portion of the mortgage universe, including Agency, Non-Agency, and Esoteric mortgage products (CES, HELOC, Reverse), including both securitized and non-securitized loans.   MLP enables full three-dimensional (borrower + loan + property) tracking with persistent keys for borrower (before and after refinancing), loan (in securities/deals even after exit due to payoffs or buyouts, including before and after MSR sales), and property.  This enables end-to-end analysis of each borrower’s (and property’s) mortgage experience throughout their credit lifecycle.  Is Downward-Trending Credit Score a Signal for Impending Delinquency?  MLP contains thousands of fields describing each loan, borrower, and property across all U.S. mortgages.  It allows for virtually unlimited segmentation and granular analysis.   For purposes of this illustrative article, we’ll take a high-level look at the entire U.S. mortgage market and perform a quick analysis to confirm intuition that a declining credit score provides a signal for higher likelihood of near-term mortgage delinquency.  Figure 1 illustrates the current pay status (as of 6/30) for the entire U.S. mortgage market, as contained in the MLP dataset, along with count, UPB and UPB-weighted Vantage 4.0 credit score for each bucket.  Figure 1  Source:  Experian Mortgage Loan Performance dataset  As illustrated in Figure 1, approximately 772,000 individual mortgage loans were reported to Experian as 30 days delinquent as of 6/30/2026.  Of the 772,000 30d delinquent loans in the June snapshot, approximately 426,000 were current in the prior (May) snapshot.  Some of these 426,000 loans were reperformers which had been bouncing from 30 DPD to current over the prior few snapshots. To remove reperformance score noise, we further parsed out the population which: 1) had rolled from current to 30 DPD from May to June; and 2) was consistently current for a full year prior to the 6/30 missed payment.  The population meeting both conditions totaled approximately 123,000 loans.  Figure 2 below shows, for this population of 123,000 “clean current” loans, the UPB-weighted average Vantage4 credit score for each of the 12 months leading up to the June missed payment, as well as the impact of the missed payment on the 6/30 score.  Figure 2  Source:  Experian Mortgage Loan Performance Dataset  Figure 2 reveals a rather slow and steady ~20-point deterioration of score in the 12 months prior to first missed payment – as well as the 80-point drop once the missed payment hits.  When we compare this cohort’s Vantage 4.0 score trend to the broader Current population across the entire dataset in Figure 3, we see a marked difference in both absolute value and trend:  Figure 3  Source:  Experian Mortgage Loan Performance Dataset  Not only is the cohort’s starting Vantage 4.0 score lower than the broader current population, but it also displays a dropping trend (with a notable 2 to 3x acceleration in monthly score drop the month before the first missed mortgage payment) while the broader Current population’s score (of which the isolated cohort is a subset) remains rock steady.  Lastly, we present Figure 4, a histogram comparing the distribution of at-origination and as-of 5/30 (i.e., the period just before the missed June mortgage payment) credit scores for the clean current population. The distribution appears to shift toward lower credit scores. To the extent credit scores are correlated with credit risk, this shift may indicate elevated credit risk relative to origination. Since this degradation occurs during a period of perfect mortgage pay performance, it is invisible to MBS investors who lack access to current borrower credit scores. Experian MLP provides monthly refreshed credit scores for mortgage borrowers contained within the MLP database.  Figure 4  Source:  Experian Mortgage Loan Performance Dataset 

September 22, 2026 by Michael Pyatski, Perry DeFelice

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe