What is in store for Demand Deposit Accounts (DDA) in 2016?

by Guest Contributor 2 min read January 21, 2016

Attract and retain high-value demand deposit accounts

The excitement of the new year has ended, and now the big question remains: What will 2016 hold for our market and the economy? So far, we’ve seen this election year bring a volatile financial market:

  • The Federal Reserve increased short-term interest rates by 25 basis in December, and there is uncertainty if and when future increases will come
  • China’s gross domestic product is forecasted at 6.5 percent, the lowest in a quarter century
  • The Dow Jones industrial average is down 10 percent to start the year, signaling a lot of uncertainty for banks and consumers

It’s hard to find answers in a shifting financial landscape with a long list of mixed signals. The average consumer is looking on and wondering if we face another Great Recession or if the current economy is spiking a fever just before it is completely cured.

The reality, for those of us in the banking industry, is that the modest economic recovery is likely to continue as part of a new normal pattern. In 2016, banks that remain competitive in a more digital world will be those that have frictionless products and processes to attract and retain high-value, highly sought-after consumer deposits and loans.

Banks should expect the competition for deposits to intensify, and they will need to ensure that new deposit customers are on boarded effectively and cross-sold loan products quickly to reduce first-year attrition. Cross-selling at the point of origination for the demand deposit account (DDA) customers is the best way to ensure that new customers keep the institution as their primary bank.

Financial institutions can exceed consumer expectations and ensure a competitive business model by leveraging modernized technology capabilities fully in combination with making relevant decisions to deliver consumer-friendly experiences. First-year DDA attrition rates will demonstrate how the consumer’s expectations were met and if the new bank got the account-opening process right or wrong.
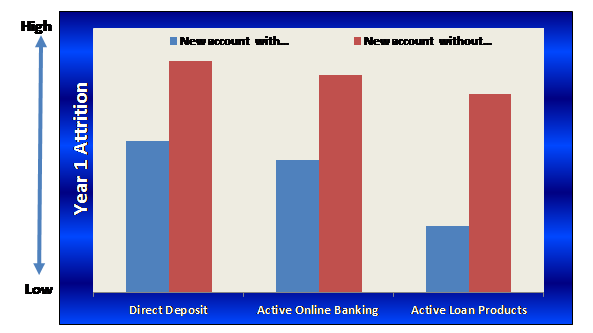
direct deposit accountExperian® suggests three capabilities clients should consider:

  • A deposits technology platform that offers frictionless change to data, origination strategies and instant cross-sell to loan products that yield sticky customers
  • Strategies that comply with current and evolving regulatory demands, such as those being sought by the Consumer Financial Protection Bureau (CFPB)
  • Business planning to identify execution gaps and a road map to ensure that gaps are addressed, confirming continued competitive ability to attract high-value deposit and loan customers

DDA-account opening effectiveness can be achieved by using a consumer’s life stage, affordability considerations, unique risk profile and financial needs to on board optimally and grow those high-value consumers effectively and efficiently. Financial institutions that are nimble and fast adopters of these critical capabilities will reduce operating expenses for their organizations, grow sustainable revenue from new prospects and customers, and delight those new customers along the way. This is a win-win for banks and consumers.

Join me next week as we discuss best practices across the entire demand deposit account life cycle.


Related Posts

2027 Data Breach Forecast: Why Trust Is Becoming the Next Cybersecurity Battleground

AI, digital doppelgängers and growing consumer skepticism could reshape the data breach landscape in 2027. Here’s what to prepare for.

September 29, 2026 by Laura Burrows
2026 Fintech Identity and Fraud Report

Explore the Fintech Identity and Fraud Report for insights on AI-driven fraud threats, identity protection and the evolving fraud landscape.

September 28, 2026 by Laura Davis
Who’s Driving What? How Fuel Loyalty and Generational Preferences are Shaping the Vehicle Market

Take a look around at any road, parking lot, or highway, and you’ll see just how diverse today’s vehicle landscape has become. Within that evolving mix, electric vehicles (EVs) have seen years of rapid growth, and while the market is seemingly entering a new phase, interest remains. So, with several vehicles and fuel types to choose from, what keeps drivers coming back to electrified vehicles? Experian Automotive’s Automotive Market Trends Report: Q2 2026 found that among EV owners who returned to the market in the last 12 months, majority (72.2%) replaced their EV with another EV, while 18.5% switched to a gasoline vehicle. Hybrid buyers also showed considerable loyalty to electrification, with 55.7% of gas-hybrid owners staying with the same fuel type when replacing their vehicle, and 32.7% swapping for a gasoline vehicle. Consumers are seemingly remaining loyal to EVs and hybrids because they are attracted to the benefits that fit their everyday lifestyle, such as lower fuel or charging costs amid the elevated gas prices. For some, it could also be tied to convenience, as drivers who have found a reliable charging routine or appreciate the efficiency of a hybrid may have little reason to switch back to a traditional gasoline vehicle. Generations are taking different paths to electrification Generational differences also influence hybrid and EV loyalty, with younger consumers generally showing greater openness to alternative fuel types. While older generations tend to have greater familiarity with traditional gasoline vehicles, hybrid and EV adoption is increasing across all age groups as these options become more accessible and mainstream. Millennials, in particular, showed the strongest inclination toward electrified vehicles. Through Q2 2026, they accounted for the highest EV share at 8.2%, compared with Gen X at 5.5%, Gen Z (4.7%), and Baby Boomers (4.7%). The difference becomes even more pronounced when hybrids are in the mix, as 23.1% of Millennial registrations were gas-electric hybrids or plug-in hybrids, versus 16.7% for Gen X, 16.8% for Gen Z, and 18.0% for Baby Boomers. For automotive professionals, these differences make understanding who is driving what, and what they may choose next, increasingly important. The future of the automotive market may be less about consumers choosing one vehicle type over the other and more about understanding the distinct patterns and preferences of each generation. As the market continues to evolve, those insights can help automotive professionals better meet consumers where they are. To learn more about vehicle market trends, view the full Automotive Market Trends Report: Q2 2026 presentation on demand.

September 24, 2026 by John Howard

Subscribe to our Newsletter

Enter your name and email for the latest updates.

This site is protected by reCAPTCHA and the Google Privacy Policy and Terms of Service apply.

Subscribe to our Newsletter

Don't miss out on the latest industry trends and insights!
Subscribe
