 Edited by Peggy Bennett
What Is a Billing Cycle?
Edited by Peggy Bennett
Quick Answer
Credit card billing cycles last for about a month and the transactions during the cycle, plus your previous balance, determine your next statement balance and minimum payment. The bill will be due in several weeks, but the next billing cycle starts immediately.
A credit card's billing cycle is the approximately one-month period between statements' closing dates. Also called a billing period or statement period, your new transactions during this time will impact your next credit card bill. Understanding how billing cycles work can be important because you can time purchases and payments to better manage your finances and credit scores.
How a Credit Card Billing Cycle Works
A credit card's billing cycle is generally 28 to 31 days long. The transactions during the billing cycle are added to your previous balance (if any) and determine your statement balance at the end of each cycle. Your bill will then be due a few weeks later, and a new billing cycle starts right away.
Example: If your card's balance is $1,000 at the end of your current billing cycle, your credit card statement will be created showing that as your new balance. Your minimum payment will be based on this amount and is often due 21 to 25 days later.
Then the next billing cycle starts, and new transactions can impact your current balance. These include:
- Purchases
- Balance transfers
- Cash advances
- Interest charges
- Fees
- Payments
- Statement credits
At the end of the next billing cycle, your statement balance will be the sum of the previous balance and these transactions.
Example: If you paid the previous $1,000 balance in full, made $1,250 in purchases and received a $50 statement credit, your new balance will be $1,200.
Credit card bills are due on the same date each month—or the next business day if the due date falls on a holiday or weekend. But because months have a different number of days, the exact length of the billing cycle may vary from one month to the next.
Credit card statements will tell you the closing date for the associated billing cycle. You can also check your current billing cycle's closing date by logging in to your online credit card account.
Best credit cards of 2026
Compare cards from our partners with intro bonuses, cash back or points offers, and annual fees as low as $0.
Offers from our partners
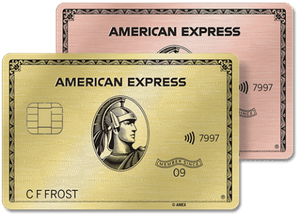
American Express® Gold Card
Intro bonus:
As High As 100,000 points. Find Out Your Offer.
You may be eligible for as high as 100,000 Membership Rewards® Points after spending $8,000 in eligible purchases on your new Card in your first 6 months of Membership. Welcome offers vary and you may not be eligible for an offer.
Ongoing APR:See Pay Over Time APR
Rewards:
1x - 5x (Points per dollar)
Earn 4X Membership Rewards® points per dollar spent on purchases at restaurants worldwide, on up to $50,000 in purchases per calendar year, then 1X points for the rest of the year. Earn 4X Membership Rewards® points per dollar spent at US supermarkets, on up to $25,000 in purchases per calendar year, then 1X points for the rest of the year. Earn 5X Membership Rewards® points on prepaid hotel stays booked through AmexTravel.com or the Amex Travel App™. Earn 3X Membership Rewards® points on flights booked through AmexTravel.com, the Amex Travel App™, or purchased directly from airlines. Earn 2X Membership Rewards® points on prepaid car rentals booked through AmexTravel.com or the Amex Travel App™ and cruises booked and paid through AmexTravel.com. Earn 1X Membership Rewards® point per dollar spent on all other eligible purchases.
Annual Fee:$325
Avant® Cashback Rewards Mastercard®
Ongoing APR:35.99%*
Rewards:
1% (cash back)
Cash back will be awarded as points redeemable for a statement credit
Annual Fee:$75*
Credit One Bank® Platinum Rewards Visa® Card
Ongoing APR:29.74% Variable
Rewards:
1% (cash back)
Earn 1% cash back rewards on eligible gas, grocery purchases and mobile phone service, internet, cable and satellite TV services, terms apply
Annual Fee:$39
Delta SkyMiles® Gold American Express Card
Intro bonus:
As High As 80K Miles + $250 Statement Credit
You may be eligible for as high as 80,000 Bonus Miles and a $250 Statement Credit after you spend $3,000 in eligible purchases on your new Card in your first 6 months of Card Membership. Apply to find out your offer. Terms Apply. Offer ends 11/04/2026.
Ongoing APR:19.74%-28.74% Variable
Rewards:
1x - 2x (Miles per dollar)
When you use your Delta SkyMiles® Gold American Express Card, you can earn: 2X miles on Delta Purchases, 2X miles at restaurants, 2X miles at U.S. supermarkets, 1X miles on all other eligible purchases. Every mile you earn brings you closer to the places you want to go. Turn them into your next trip, use them for seat upgrades, and more.
Annual Fee:$0 introductory annual fee for the first year, then $150.
Delta SkyMiles® Blue American Express Card
Intro bonus:
10,000 Miles
Earn 10,000 bonus miles after you spend $1,000 in purchases on your new Card in your first 6 months.
Ongoing APR:19.74%-28.74% Variable
Rewards:
1x - 2x (Miles per dollar)
Earn 2X Miles per dollar at restaurants worldwide, plus takeout and delivery in the U.S. Earn 2X Miles per dollar spent on Delta purchases, and 1X Mile on all other eligible purchases.
Annual Fee:$0
Citi Simplicity® Card
Intro APR:0% intro APR for 18 months from account opening on purchases and qualifying balance transfers
Ongoing APR:17.74% - 28.49% (Variable)
Rewards:
N/A
Annual Fee:$0
Hilton Honors American Express Aspire Card
Intro bonus:
200,000 Points
Best Points Offer Yet! Earn 200,000 Hilton Honors Bonus Points with the Hilton Honors American Express Aspire Card after you spend $6,000 in purchases on the Card within your first 6 months of Card Membership. Offer ends 01/13/2027.
Ongoing APR:19.74%-28.74% Variable
Rewards:
3x - 14x (Points per dollar)
Earn 14X Hilton Honors Bonus Points when you make eligible purchases on your Card directly with hotels and resorts within the Hilton portfolio. Card Members can earn 7X Points on purchases of Flights booked directly with airlines or flights booked through American Express Travel, Car rentals purchased directly from select car rental companies, and purchases at U.S. Restaurants. Card Members can earn 3X Points on all other eligible purchases.
Annual Fee:$550
Avant® Cashback Rewards Mastercard®
Ongoing APR:29.99%*
Rewards:
1% (cash back)
Cash back will be awarded as points redeemable for a statement credit
Annual Fee:$0*
See all our best credit cards for 2026.
How Your Billing Cycle Affects Your Credit Score
The length and timing of your billing cycle don't directly impact your credit scores. But knowing when your billing cycle ends can be important because credit card issuers generally report your account's information to the credit bureaus around this time. The information they report will then appear in your credit reports, which is what your credit scores are based on.
The reported balance can be particularly important as it determines your credit utilization ratio. This ratio is calculated by dividing the account's balance by its credit limit, as they appear on your credit report, and a high utilization ratio can hurt your credit scores.
Example: If your reported balance is $1,000 and your credit limit is $2,000, your utilization rate for that card is 50%. That's considered high and can impact credit scores. In general, always try to keep your utilization under 30%, and the lower, the better.
Because credit card balances are often reported at the end of each billing cycle, you could have a high utilization ratio even if you pay your bill in full each month. However, if you know when your billing cycle will end, you could pay down the account's balance early, decrease the reported balance and potentially improve your credit score by lowering your utilization ratio.
Can You Change Your Billing Cycle?
You can indirectly change your billing cycle by changing your bill's due date. Modifying your due date means your billing cycle will automatically be shifted to align with the new due date. But check the company's rules before requesting a change, as there may be limits on how often you can request a change. The change also might not start for a few billing cycles.
Choosing a new due date won't impact your account's interest rate, grace period or how much interest accrues. But having all your bills due on the same date each month could make managing your payments easier.
You can also time major purchases based on your card's billing cycle. For example, if you make a major purchase at the start of a new billing cycle, you could have about 50 days before the bill is due. And if you pay your credit card bill in full each month, you won't be charged interest on purchases.
Monitor Your Credit Scores
You can check your FICO® ScoreΘ for free from Experian to see how your score changes from one month to the next. Many credit scoring algorithms only consider your most recently reported credit card balances and limits, and the resulting utilization ratios, when calculating your score. If a high utilization ratio is hurting your credit scores and you can pay down cards' balances before the end of their billing cycles, you might be able to improve your scores.
Don’t apply blindly
Apply for credit cards confidently with personalized offers based on your credit profile. Get started with your FICO® Score for free.
See your offers
About the author

Louis DeNicola
Louis DeNicola is freelance personal finance and credit writer who works with Fortune 500 financial services firms, FinTech startups, and non-profits to teach people about money and credit. His clients include BlueVine, Discover, LendingTree, Money Management International, U.S News and Wirecutter.
Read more from Louis